Shannon Boakes
Investment & Wealth Advisor, Financial Planner
September 1, 2026
For a lot of the women I work with, the question was never “should I be saving?” They've been saving for years, often well, and it shows. The real question, the one that rarely gets asked out loud, is quieter and a little more uncomfortable: is the money actually doing what it should be doing, or has it just been sitting where it landed?
That's the risk I want to talk about this month, because at this stage it isn't the one most people expect. It isn't a lack of discipline or a missed contribution. It's structure. Accounts opened years or even decades ago, for a different income, a different life stage, a different set of goals, that never got revisited once the balance grew and the picture changed. Cash sitting in the wrong place. Registered room going unused year after year. Investments held in a way that quietly creates more tax than it needs to. None of it looks like a mistake from the outside. It just looks like money that's been left alone.
Here's the shift I want to make in this conversation: there's no single “best” savings account. There's the right vehicle for this capital, this objective, this timeline, and this tax situation. And when you have more to work with, the cost of getting that wrong, idle cash earning next to nothing, unused registered room, tax drag on investments that could be structured more efficiently- is measured in real dollars. Often a lot of them.
Matching Capital to Objective, Beyond the Basic Account
Most conversations about savings accounts start with “what is a TFSA” or “how does an RRSP work.” That's not this conversation. You already know the basics, likely better than most. What's worth walking through instead is how each of these vehicles fits into a bigger picture, not as a product to open, but as a tool that either is or isn't pulling its weight for the capital you actually have.
The TFSA: More Than a Parking Spot
The TFSA is, in my experience, the most underused tool among the women I work with, not because they don't have one, but because of how it's being used. It gets treated as a holding pen for cash between decisions, when it's actually one of the most tax-efficient long-term growth vehicles available. Every dollar of growth inside it, forever, is yours. At this level, letting that room sit half-used, or filled with cash instead of investments positioned to actually grow, is a quiet and completely avoidable cost.
The RRSP: Not Just About Now
The RRSP does the job most people know it for, tax-deferred growth and a deduction today, but the more important question for an experienced investor is what happens on the other end. How this account gets drawn down, in what order, and alongside what other income, has real consequences for your tax bill in retirement and for what eventually passes to the people or causes you care about. An RRSP built without a withdrawal and estate strategy attached to it is only half a plan.
FHSA and RESP: Purpose-Built, Not Small Money
It's easy to overlook the FHSA and RESP once your own accounts have grown, on the assumption that registered accounts this specific must be for smaller sums or earlier life stages. That assumption costs families real money. A First Home Savings Account for an adult child, or an RESP for a grandchild, is a genuinely tax-efficient way to direct capital toward a goal that matters to you, often with government contributions layered on top. These accounts deserve a place in the bigger strategy, not a footnote.
Non-Registered and Corporate Accounts: Where the Real Complexity Lives
Once the registered accounts are optimized, this is where the real work happens for high earners and business owners. Which investments sit in which account, asset location, matters more than most people realize; interest income, dividends, and capital gains are taxed differently, and where you hold each type of investment can meaningfully change what you keep. For business owners, the question extends further still, into how investments are held inside the corporation versus personally, and what that means for both tax efficiency and long-term flexibility. This is rarely a do-it-yourself decision, and it's exactly the kind of complexity a good advisor should be actively managing on your behalf.
High-Interest Savings and GICs: The Right Home for Short-Term Reserves
These vehicles absolutely have a place, for a true emergency reserve, for capital earmarked for a near-term purchase, for money that genuinely shouldn't be exposed to market movement. What I'd caution against is letting comfort turn into habit. At this level, too much cash sitting idle, beyond what's actually needed for short-term reserves, is its own quiet cost. It feels safe. It's rarely efficient.
These are the questions I hear most often once someone starts looking at their accounts with this lens:
“Where should I put money once my registered accounts are maxed out?”
“How do I reduce tax on my investments?”
“What's the best way to structure savings when you have a high income?”
There isn't a generic answer to any of these. The right answer depends entirely on your income, your goals, your timeline, and how the pieces you already have fit together, which is exactly why this is a conversation worth having directly rather than defaulting to whatever structure has always been in place.
Why Getting This Right Carries Higher Stakes for Women
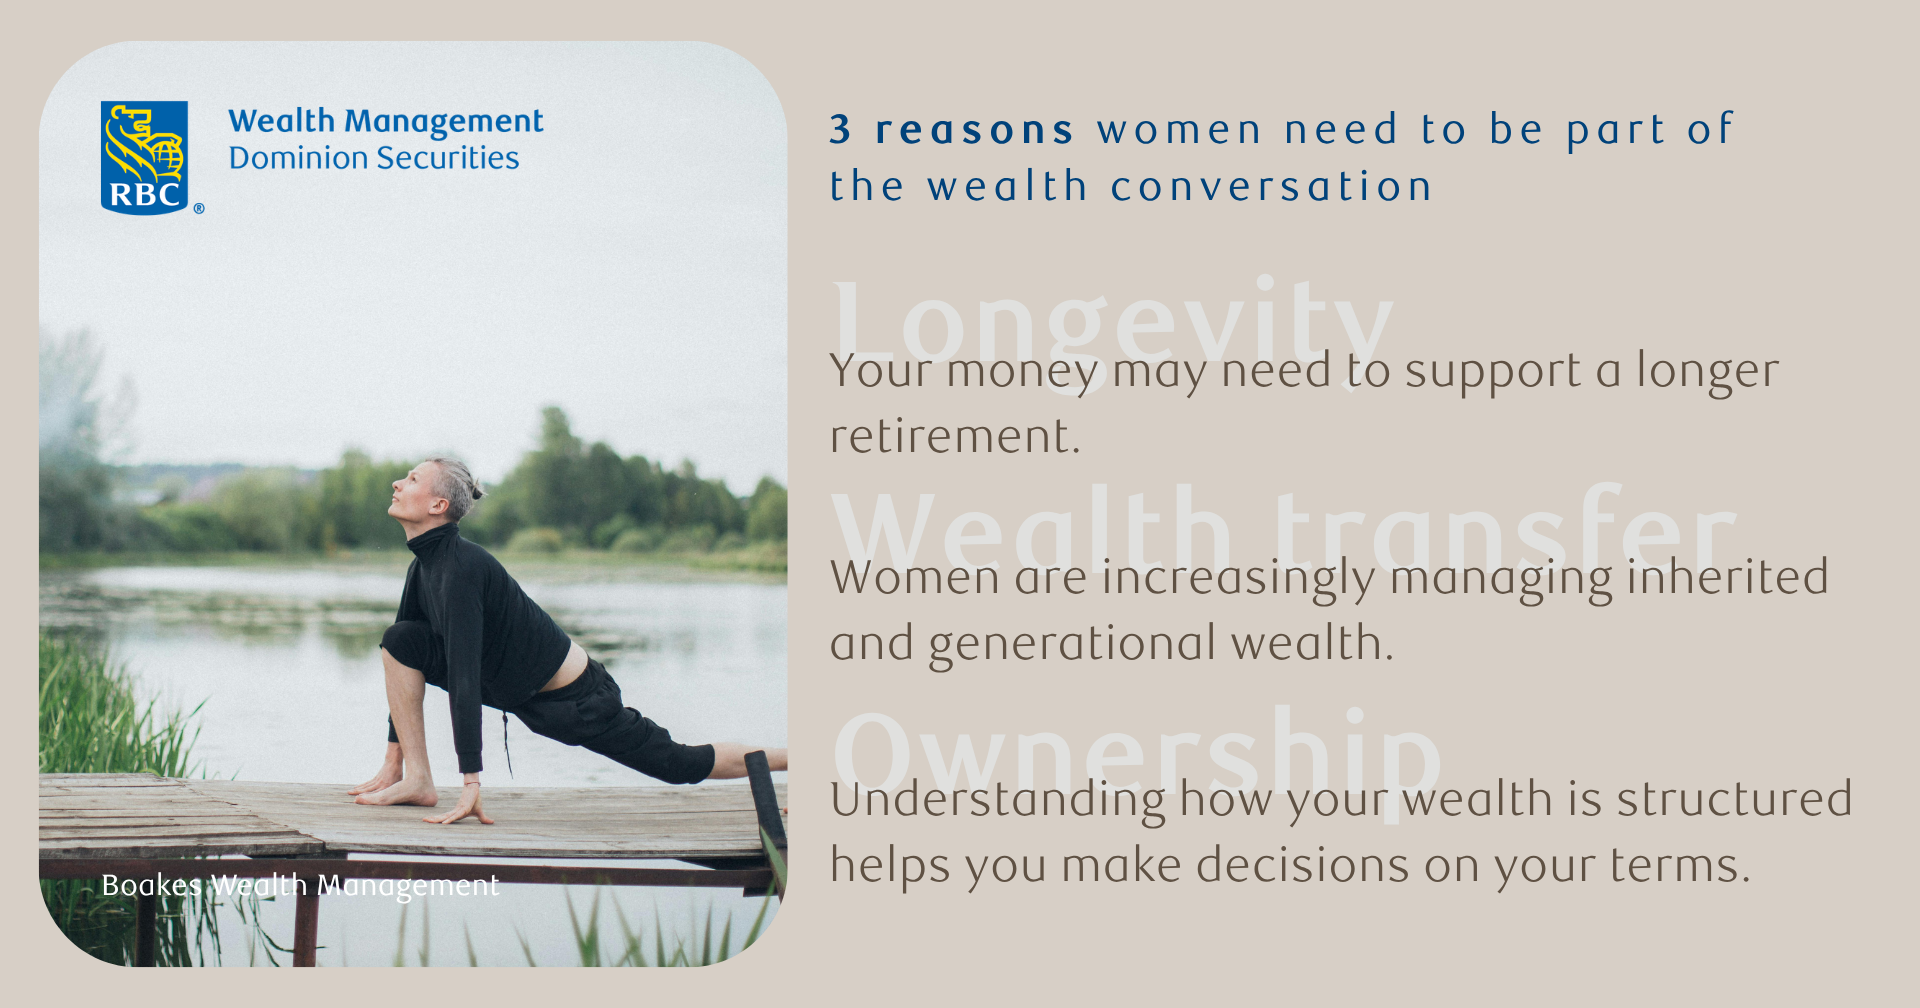
There are a few realities that make this conversation more consequential for women, not less. Women tend to live longer, which means the money has to last longer and stay tax-efficient over a longer horizon, not just accumulate. Women are increasingly likely to inherit more than once, first from parents, later from a spouse, and are controlling a growing share of household and generational wealth as a result. And yet, even now, women are too often left out of the detailed strategy conversation about that wealth, even when it's unquestionably theirs.
I want to reframe something here, because I think the usual narrative gets it backwards. The risk for the woman reading this isn't that she's too cautious with her money. It's that she's been under-engaged in her own structure, not by choice, but because an advisor defaulted to speaking with her spouse, or assumed a high-level summary was enough for someone who was clearly capable of more. Sophisticated women deserve the sophisticated version of this conversation, the same depth, the same detail, the same respect for their capacity to understand it, that would be extended automatically to anyone else in the room.
And here's the empowering part of this, because I don't want this to read as one more thing to worry about. Taking ownership of how your capital is structured isn't about learning to save, you've already done that, and done it well. It's about making sure your wealth is as intentional and as efficient as you are. It's about building something that can carry you through a long life, adapt as your circumstances change, and pass on cleanly, on your terms, to the people or causes you choose.
“How do I make sure my money lasts if I live longer than my spouse?”
“How do affluent women plan for inheritance and wealth transfer?”
“Is my money working as efficiently as it should be?”
These aren't small questions, and they don't have quick answers. But they're the right questions, and asking them directly, rather than assuming someone else is already asking them on your behalf, is where a more efficient, more intentional structure actually begins.
Final Thoughts:
Structure isn't the exciting part of wealth management, but it's often where the most real, most recoverable value gets left on the table. Not because of a bad decision, but because of a good decision made years ago that was never revisited. The women I work with haven't failed at saving. What they deserve now is a plan that matches the sophistication of what they've already built.
- So here's where I'd invite you to start, not with a spreadsheet, but with a few honest questions:
- When did I last review where my money actually sits, account by account?
- Is my registered room being used with intention, or just left alone?
- Do I understand why my investments are held where they are, and whether that's still the right call?
- Have I had a real conversation about how this all carries forward, to me, and eventually to the people I care about?
If any of those gave you pause, that's worth acting on. At Boakes Wealth Management, we believe the women we work with deserve more than a generic account recommendation, they deserve a structure built around the life they've actually built. Let's make sure your money is working as intentionally as you are.
Because efficient, well-structured wealth isn't just about what you keep today. It's about what carries forward, cleanly and on your terms.
Shannon
Shannon Boakes, CFP, FMA, CIWM, FCSI | Investment amp; Wealth Advisor, Financial Planner, RBC Wealth Management | RBC Dominion Securities | T. 519-758-1270 | C. 226-208-0357 | 22 Colborne Street, 2nd Floor Brantford, ON N3T 2G2 | www.boakeswealthmanagement.com
This community extends beyond one conversation. It’s built through shared ideas, thoughtful planning, and staying connected over time.
Follow along on LinkedIn and Facebook, or reach out if you’d like to talk through your own situation or refer someone who could use support.
Boakes Wealth Management is welcoming a few new clients, especially business owners and families approaching retirement. Know someone who'd be a good fit? Let’s connect!
RBC Wealth Management is a business segment of Royal Bank of Canada. For further information on the entities that are member companies of RBC Wealth Management, click here. The content in this publication is provided for general information only and is not intended to provide any advice or endorse/recommend the content contained in the publication.
® / ™ Trademark(s) of Royal Bank of Canada. Used under licence. © Royal Bank of Canada 2026. All rights reserved.