Jamie Burak
Senior Investment and Wealth Advisor
September 30, 2026
Friends & Partners,
Before anything else this month, we want to lead with the number that matters most: the portfolio is having a good year. The Canadian model is up substantially across nearly every core position, and the U.S. side is holding its own, and in many cases outperforming, the broader market on a like for like basis. We want to say that plainly up front, because the rest of this letter is going to spend some time on rates, breadth, and a choppy September, and we do not want that discussion mistaken for worry. It is context, not concern.
The S&P 500 sits close to an all time high, and the NASDAQ 100 is up nearly 21% for the year. Those headline numbers are real, but they are also more concentrated than they first appear, and understanding that concentration is actually good news for how this portfolio is built. We will walk through that below, along with the rate and breadth backdrop, and what we did in the portfolio this month.
Here is our thesis in one sentence: this year's gains have been driven by a narrower slice of the market than the headlines suggest, our portfolio is built for broader, more durable participation, and with earnings strong and the labor market tight, we expect that to keep paying off. We also kept this month's trading light on purpose, one trim, described below, rather than a long list of changes.
Market Overview: September 2026 in Review
Index | 1-Month | 2026 YTD |
|---|---|---|
S&P 500 (SPY) | -0.39% | +12.38% |
NASDAQ 100 (QQQ) | +3.74% | +20.99% |
TSX 60 (SXO) | -3.03% | +11.78% |
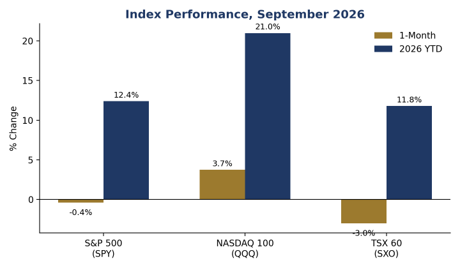
Index performance, 1-month and year-to-date, through September 30, 2026
The NASDAQ 100 still posted a solid gain this month, but the S&P 500 and the TSX both slipped modestly, and as the tables below will show, the index level understates just how uneven the month was beneath the surface.
Why the Nasdaq's Gain Looks Bigger Than It Is
It is worth being precise about where this year's biggest headline numbers are actually coming from, because it changes how you should read them. The Magnificent 7, as a group, are up only about 9% year to date, a modest number by their own historical standards. Meanwhile memory chip names, Micron chief among them, are up roughly 275% this year on the back of AI driven demand for chips. A handful of enormous moves in a small number of names are doing a lot of the work behind the NASDAQ 100's headline return.
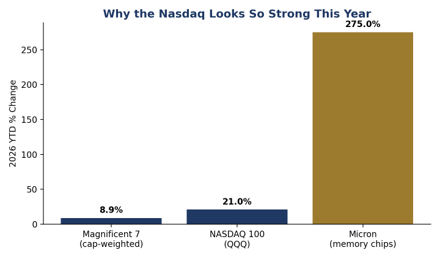
2026 year-to-date performance. Sources: FactSet and public market data, as of September 30, 2026.
What Happened This Month, and Why It Does Not Change Our View
Breadth narrowed in September. By several measures, the percentage of stocks trading above their short and medium term averages fell to levels that are historically oversold. The median stock in the S&P 500 spent the month meaningfully below its own 52 week high, even as the index sits near a record. This is a real, measurable pattern, and it explains why a number of good businesses we own were red on the month even while the year overall remains strongly positive.
Rates, driven by oil, were the proximate cause. The 10 year Treasury yield climbed to its highest level in nineteen years this month, tracking almost in lockstep with crude oil, which is up sharply as the Middle East conflict continues. Markets are pricing a high probability of another Fed rate hike by year end. Higher for longer rate expectations tend to pressure richly valued and rate sensitive names first, which is the pattern behind this month's dip in several holdings.
And the fundamentals underneath remain genuinely strong. S&P 500 earnings are on pace to grow close to 29% year over year in the third quarter, the third straight quarter of growth above 25%, broad based across sectors. The U.S. labor market remains tight, with unemployment holding at 4.1%. A market grinding through a rate driven wobble while earnings grow this fast and unemployment stays this low is, in our view, a market working through noise, not a market with a real problem.
Oil is the variable to watch. If the Middle East conflict continues to escalate, oil and rates likely stay elevated for a while longer. But there are early signs of a path toward de-escalation, with talks between the United States and Iran underway, and once the geopolitical premium in oil fades, the pressure on bond yields has tended to fade with it. We are watching this closely, it is the single biggest swing factor in our near term outlook, but it is a variable to monitor, not a reason for concern about the portfolio's positioning.
Portfolio Changes: What We Did and Why
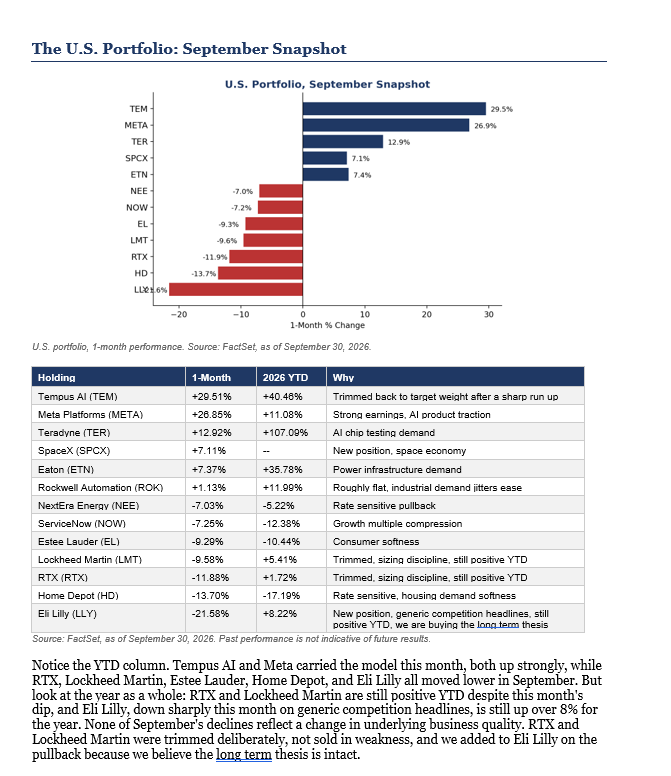
Trimmed Tempus AI back to its original allocation. This was our only change this month. Tempus AI has had a quick, sharp run up, up nearly 30% in September alone, and names that move this fast in this short a window have a history of giving back a meaningful chunk of those gains shortly after. Rather than chase the position further or hold an outsized weighting, we trimmed it back to the allocation we originally intended, locking in some of the gain while keeping full exposure to the underlying thesis. This is sizing discipline, not a change in conviction, we remain happy holders of the position at its target weight. Last month's changes, the JEPI to XGD swap in Canada and the exits, adds, and trims on the U.S. side, were covered in detail in September's letter and remain unchanged this month.
The Broader Picture
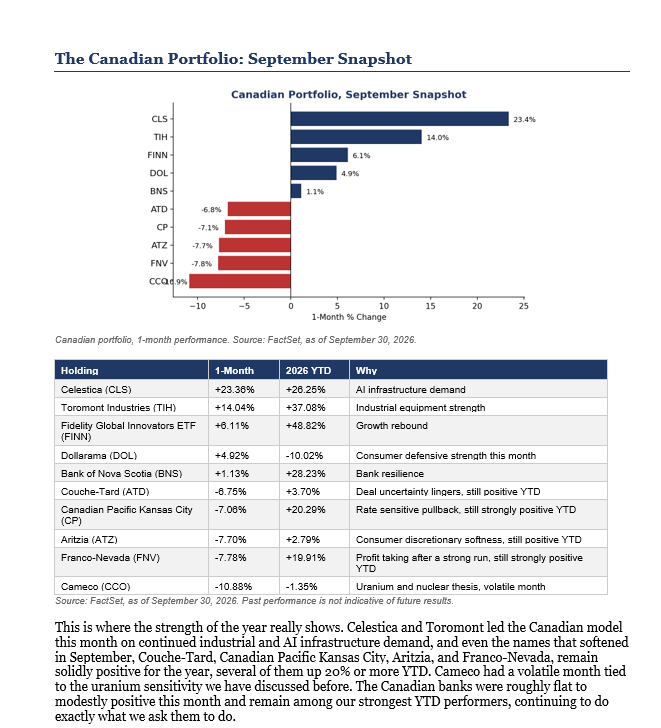
Our Conviction. We believe in this portfolio, and the numbers back that up. The Canadian model is having a strong year across nearly every core position, and the U.S. side is holding its own against the broader market without needing to chase the handful of extreme single stock moves driving this year's headline index returns. September was a choppier month, rates rose and breadth narrowed, but earnings are growing close to 29% and unemployment sits at 4.1%. We expect the names that softened this month to keep reflecting that underlying strength as the rate and oil pressure eases.
What Would Change Our View. A genuine escalation in the Middle East that keeps oil and rates elevated indefinitely, or a real crack in earnings or employment data, would both cause us to reassess. Neither has happened yet, and we are watching both closely.
October Planning Focus: Finish the Year With a Plan
With the fourth quarter underway, this is the ideal window to get ahead of year end planning rather than scrambling into December. Tax loss and tax gain planning, RRSP and TFSA contribution room, year end gifting, and any life changes coming in the new year are all easier to plan for now than later. If there is anything on your mind for the months ahead, let us know and we will build your year end review around it.
Closing Thoughts
This has been a strong year for the portfolio, and September's rate driven wobble does not change that. The fundamentals behind this portfolio, strong earnings, a tight labor market, and long term positions in businesses we believe in, remain firmly in place, and the results so far this year reflect it. We used this month's weakness to add to several of those positions rather than retreat from them, and we will continue to do so as long as the underlying thesis holds.
As always, if any of this raises questions about your specific accounts or your broader plan, please do not hesitate to reach out.
That conversation is always welcome, and it is always about you first.