Nick Milau
October 1, 2026
Weekly Wrap
Let’s recap the month that was before talking about this week. Global equities were mixed in September, with only U.S. equities and Emerging Markets posting gains. The real story, though, wasn’t equities – it was bonds, with Government of Canada yields jumping between 15 and 30 basis points while U.S. Treasury yields climbed 15-50 basis points pressuring both equity prices and investor sentiment overall. Developed international markets were down with investor concerns about the region’s vulnerability to rising energy costs. But the area has held up nicely YTD as it offers less exposure to AI-related themes, making them an attractive option for investors seeking diversification. Precious metals came under pressure as rising interest rates increased the opportunity costs of holding non-yielding assets such as gold and silver.
As for this week, U.S. markets are mixed as of writing with the S&P 500 eking out a gain, the Dow down by almost a percent, and the Nasdaq solidly up close to 1.5% due to cooler-than-expected September job report and retreating Treasury yields, which eased concerns over further Fed rate hikes. The TSX is in the red to the tune of 0.40% largely on the heels of the materials and financial sectors. The Emerging Market saw a sell-off this week and is in negative territory with a -1.58% return. Oil finished the week lower, and gold looks to have a second straight weekly drop.
Market Insights
Canadian cities ranked among weakest real estate markets worldwide. UBS, a global wealth management firm, published its annual Global Real Estate Bubble Index last week. It dives into price trends, bubble risks, among other metrics. UBS rates Toronto’s bubble risk as ‘moderate’ as it does Vancouver’s. From the 2022 peak, Vancouver’s prices are down about 20% with home sales sitting at 25-year lows. They also monitor something called the price-to-rent ratio which is an indicator of how long it would take a renter to have paid enough rent to own a 650 square foot apartment. In Vancouver, it would take around 23 years. The current market environment favors renters as rents continue to come down, and buyers with prices as low as they are but probably doesn’t favor investors, especially with mortgage rates creeping up.
Investment implications from the Canada Investment Summit. Over 100 global investors recently gathered in Toronto to explore Canada's investment landscape, and the numbers are compelling. A prospectus unveiled 160+ projects worth approximately US$500B across Energy, Infrastructure, and Materials—positioning Canada for a potential 10+ year investment supercycle. Unsurprisingly, energy dominates, representing nearly 50% of proposed capital investment. Major initiatives include the West Coast oil pipeline, Ksi Lisims LNG Terminal, and substantial wind energy projects like Wind West. The Power and Utilities sector features hydro-electric, nuclear, and transmission infrastructure, while over 50 mining and critical minerals projects are in various development stages. Transportation and infrastructure investments span high-speed rail, ports, AI data centres, and advanced manufacturing.
Western Canada (BC and Alberta) leads due to energy and mining exposure. Nova Scotia benefits from clean energy and port projects, though many remain early-stage. Manitoba's significant allocation is anchored by the Port of Churchill expansion—a transformative US$3.9B initial investment with US$57B eventual capital needs—critical for diversifying trade routes. Recent federal initiatives are creating tailwinds. The new Productivity Mega-Deduction slashes the marginal effective tax rate on new business investment to 6.4%. Concurrently, the expanded Build Canada Act streamlines approvals and fast-tracks major projects. Success hinges on multiple factors: improved tax and regulatory systems, reduced interprovincial trade barriers, and adequate skilled labour availability. While implementation timelines extend beyond immediate horizons, broad-based TSX sector beneficiaries are positioned to capture this infrastructure wave.
Portfolio Update
There is no portfolio update this week.
Please note any changes apply to our Private Investment Management (PIM) portfolios only, subject to restrictions. Please call to clarify if you have any questions.
Planning On
Planning On: Tax Credits & Deductions for Seniors
If you or a family member are 65 or older, hopefully you are not leaving any money on the table when it comes to taxes. Canada offers several credits and deductions specifically designed for seniors and their caregivers—and while your accountant or tax software should be prompting you about these, they are still worth knowing about.
The big hitters? The age amount can reduce your federal taxes by up to $1,289 (assuming your income sits below the phase-out threshold – the credit is reduced by $.14 for every $1 of net income above $46,432 and completely eliminated at net income of $112,203), and if you're receiving pension income, the pension income amount gives you a credit on the first $2,000 of eligible payments. Be careful with RSP withdrawals as they are not considered pension income. You would need to transfer to a RIF first and then withdraw to ensure it is eligible (and then also available for pension splitting). Any unused credits can often be transferred to your spouse.
Beyond the obvious, there are some gem-level credits worth exploring. The Disability Tax Credit opens doors for those with a severe, prolonged impairment. If you're supporting a spouse or dependent, the Canada caregiver amount can help offset costs. And if accessibility renovations are on your radar, the Home Accessibility Tax Credit offers a non-refundable tax credit of up to $2,800 for renovation expenses to improve accessibility and safety of your home.
Don't overlook medical expenses either—they can often be claimed as a credit, even if incurred outside Canada. Plus, if you're building an additional suite for a parent or grandparent 65+, the Multigenerational Home Renovation credit can hit up to $7,000.
The Canada Caregiver Amount is a non-refundable tax credit you can claim if you support a spouse or dependent who has a physical or mental impairment. The key requirement for this is that the person you are supporting must regularly and consistently rely on you for the basic necessities of life (food, shelter, and clothing).
The takeaway? The rules here are genuinely complex, and many of these credits are non-refundable (meaning they disappear if you don't use them). Work with us and a qualified tax professional to ensure you're capturing everything available to you and your family.
This information is not intended to provide legal, tax, or insurance advice. To ensure that your own circumstances have been properly considered and that action is taken based on the latest information available, you should obtain professional advice from a qualified lawyer or accountant, as applicable, before acting on any of the information.
Updates from the Team
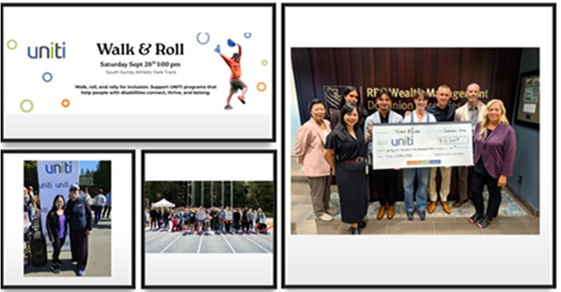
Walk & Roll for UNITI Update
On September 26th, Team Milau stepped out to walk for a cause that matters. At South Surrey Athletic Park, our team rallied together and raised $41,420 for Walk & Roll for UNITI. The event surpassed its goal and raised $105,000 across all participants! The event didn't just move the needle, it created something truly special, reminding us why community support is at the heart of who we are.
Charts of the Week
Feel free to share this newsletter with anyone who might benefit from it or find value in it. Thank you for reading our commentary. We welcome your feedback!
Return to homepage
This information is not investment advice and should be used only in conjunction with a discussion with your RBC Dominion Securities Inc. Investment Advisor. This will ensure that your own circumstances have been considered properly and that any action is taken based upon the latest available information. The strategies and advice in this report are provided for general guidance. Readers should consult their own Investment Advisor when planning to implement a strategy. Interest rates, market conditions, special offers, tax rulings, and other investment factors are subject to change. The information contained herein has been obtained from sources believed to be reliable at the time obtained but neither RBC Dominion Securities Inc. nor its employees, agents, or information suppliers can guarantee its accuracy or completeness. This report is not and under no circumstances is to be construed as an offer to sell or the solicitation of an offer to buy any securities. This report is furnished on the basis and understanding that neither RBC Dominion Securities Inc. nor its employees, agents, or information suppliers is to be under any responsibility or liability whatsoever in respect thereof. The inventories of RBC Dominion Securities Inc. may from time to time include securities mentioned herein. This publication is for information purposes only. Graphs and charts are used for illustrative purposes only and do not reflect future values or changes. Past performance is not indicative of future returns. This commentary is based on information that is believed to be accurate at the time of writing and is subject to change. All opinions and estimates contained in this report constitute RBC Dominion Securities Inc.'s judgment as of the date of this report, are subject to change without notice and are provided in good faith but without legal responsibility. Interest rates, market conditions and other investment factors are subject to change. Past performance may not be repeated. The information provided is intended only to illustrate certain historical returns and is not intended to reflect future values or returns. This publication is not intended as nor does it constitute tax or legal advice. Readers should consult their own lawyer, accountant or other professional advisor when planning to implement a strategy. Insurance products are offered through RBC Wealth Management Financial Services Inc.("RBC WMFS"), a subsidiary of RBC Dominion Securities Inc.* RBC WMFS is licensed as a financial services firm in the province of Quebec. When providing insurance products in all provinces except Quebec, Investment Advisors are acting as Insurance Representatives of RBC WMFS. In Quebec, Investment Advisors and Estate Planning Specialists are acting as Financial Security Advisors of RBC WMFS. RBC Dominion Securities Inc., RBC WMFS and Royal Bank of Canada are separate corporate entities which are affiliated. *Member-Canadian Investor Protection Fund. RBC Dominion Securities Inc. and RBC WMFS are member companies of RBC Wealth Management, a business segment of Royal Bank of Canada. â / ™ Trademark(s) of Royal Bank of Canada. Used under license. RBC Dominion Securities Inc. 2026 All rights reserved.