Brad Weatherill
Senior Wealth Advisor
August 27, 2026
When to elect to receive your CPP and OAS can be a critical retirement decision for many Canadians.
There is a long list of important factors to consider, such as retirement age, taxes, income alternatives, investment alternatives, continued employment, inflation, and life expectancy.
CPP: When Do Canadians Start Taking It?
The decision of when to start collecting CPP impacts how much money you receive each month and the total amount you receive for the rest of your life.
The Age Breakdown
- Age 60: Between 35% and 40% of Canadians start receiving CPP at age 60, but they receive 36% less money annually (than those who start receiving CPP at age 65).
- Ages 61-64: Between 40% and 50% of Canadians claim CPP during this time. Recipients face a 0.6% reduction for every month they claim CPP before age 65. That is a 7.2% reduction per year.
- Age 65: Only 15% to 19% start receiving CPP at what is considered the “standard” age.
- Ages 66-70: Only 2% to 4% wait this long, but they receive a 0.7% increase for each month they wait after age 65. This is an 8.4% annual bonus.
Here is a chart that identifies the break-even point for delaying CPP.
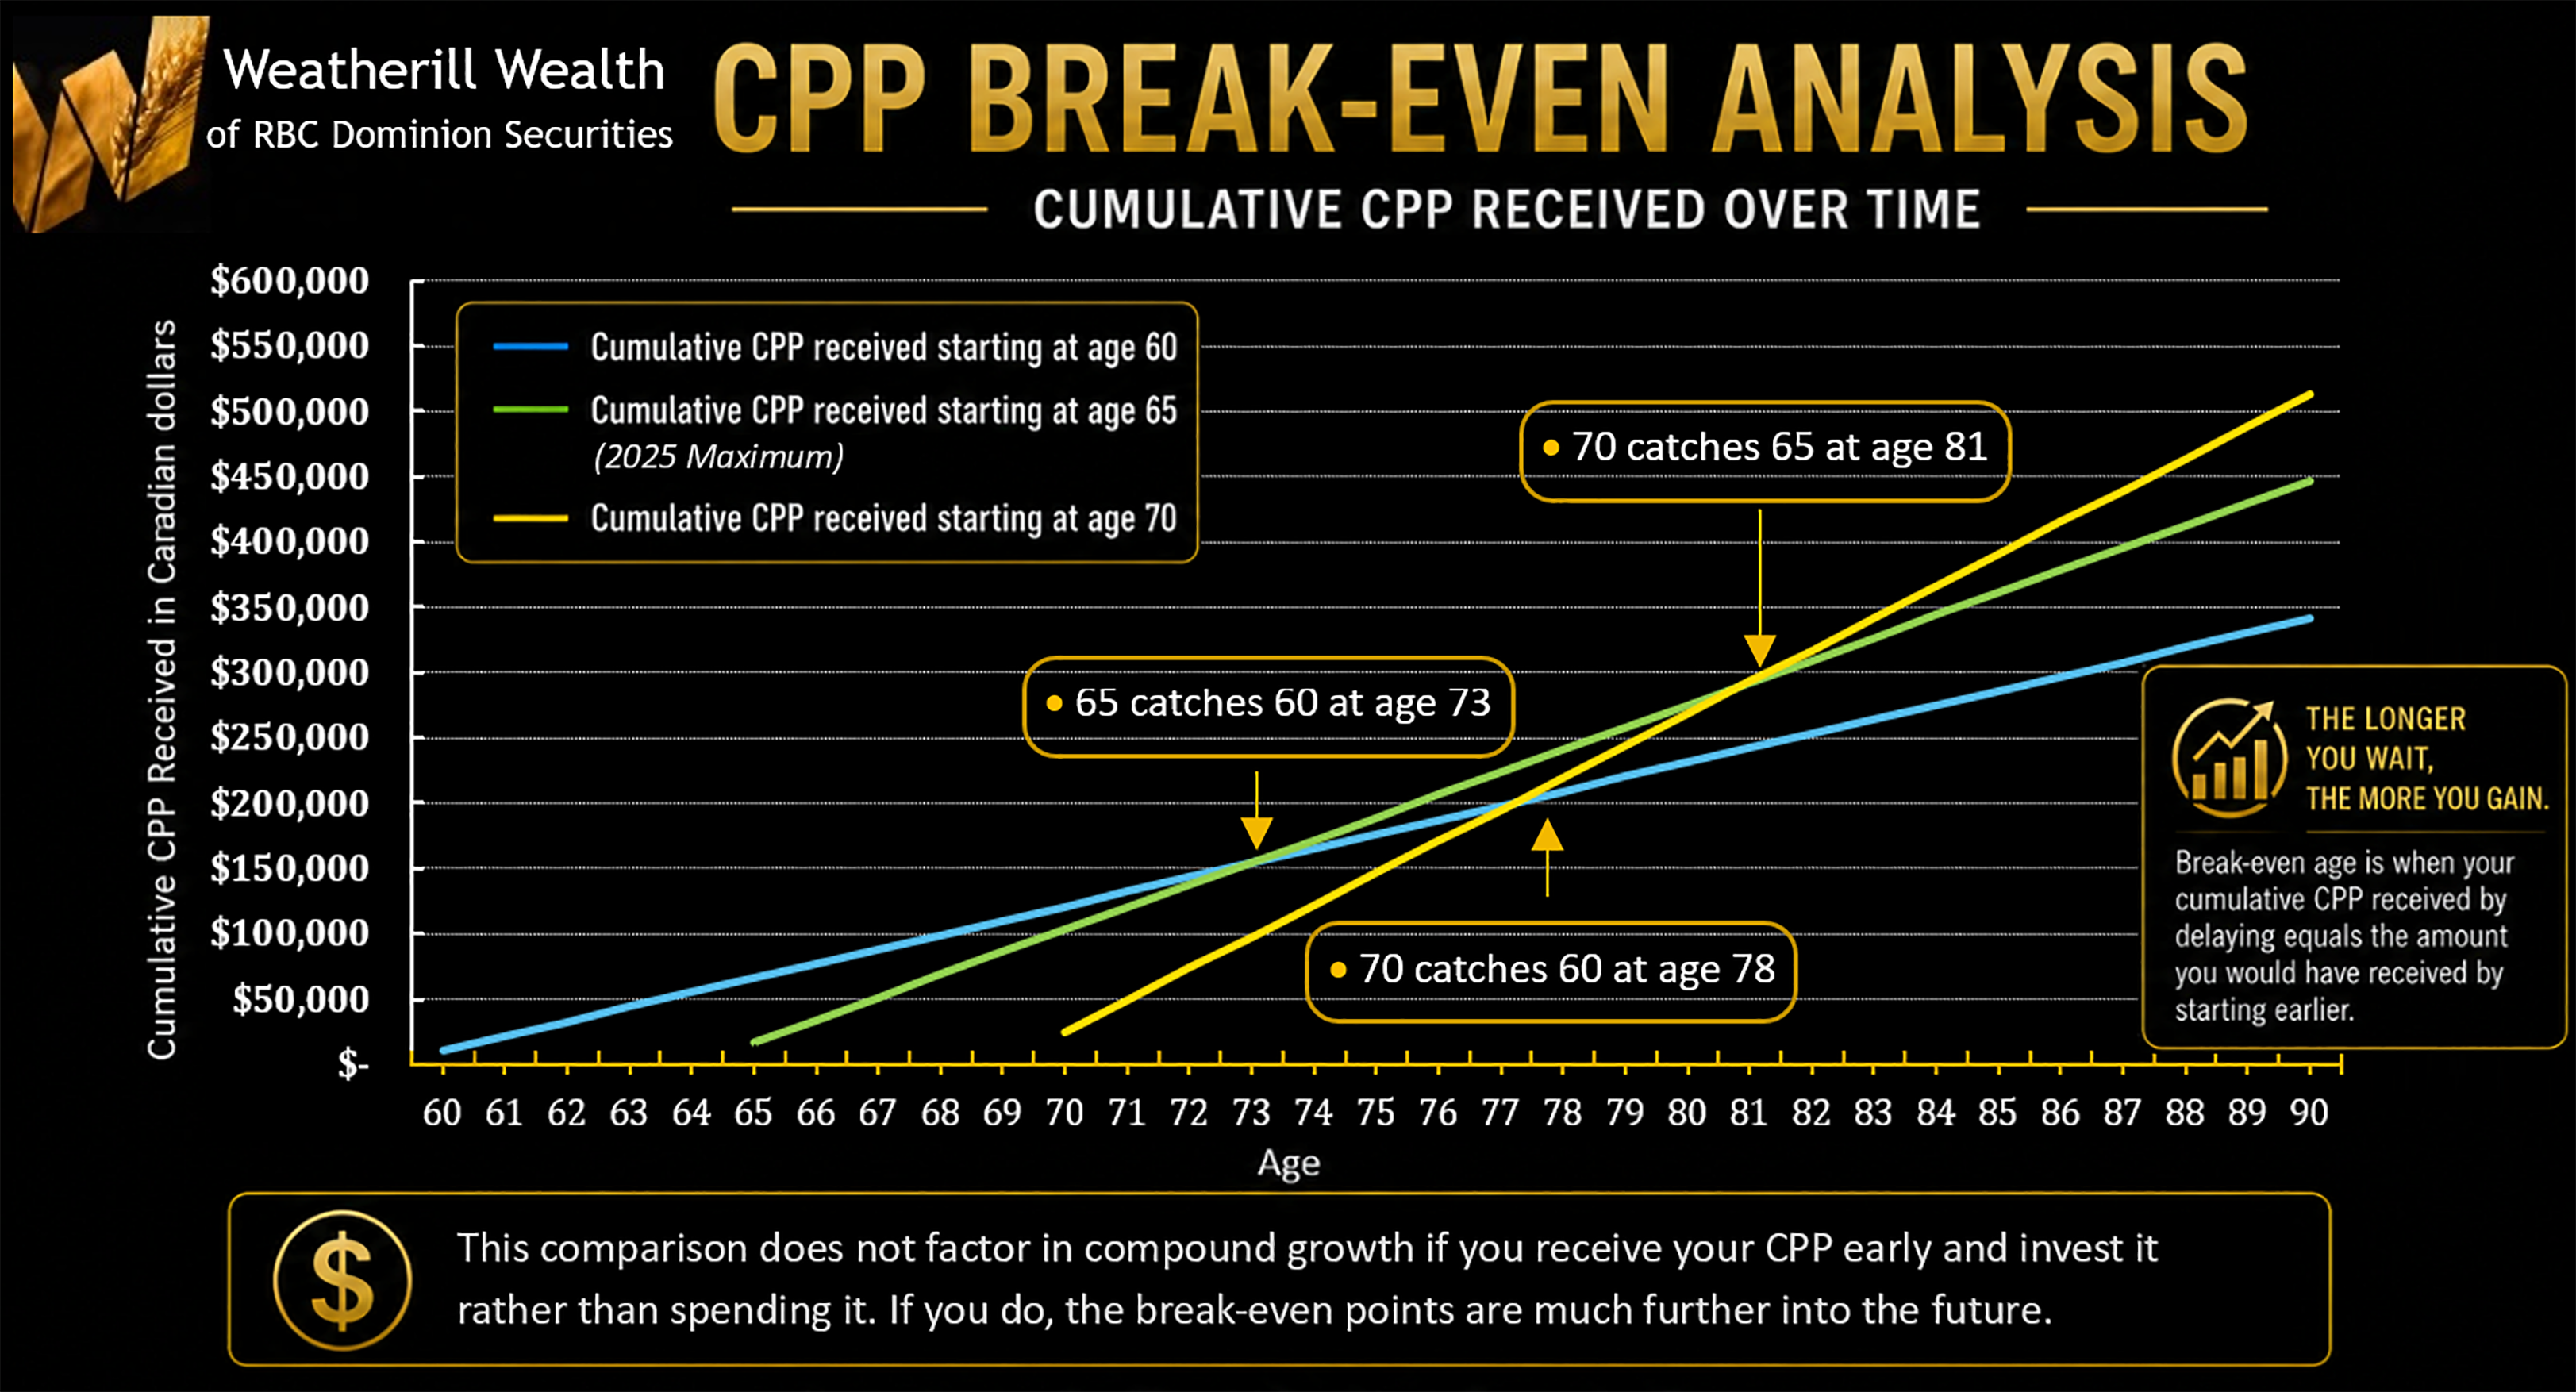
Interesting takeaway: If you start at age 70 (instead of age 60), you will receive 78% more per monthly payment, which results in $171,616 in additional income by age 90.
Less than 5% of Canadians receive their maximum CPP entitlement. Here’s why…
To get maximum CPP, you need to pay the maximum amount into CPP for 39 straight years (between ages 18 and 65). Many people go through periods where they don't earn enough to make the maximum contributions.
OAS: The Other Retirement Benefit
OAS is simpler. Old Age Security is determined by how long you have lived in Canada after the age of 18. Most Canadians will automatically get the full amount of $751.97 per month, at age 65. You don't need to have worked a certain number of years like CPP.
Not everyone receives the full OAS amount. If a recipient’s net income climbs above $95,323, the Canada Revenue Agency claws back a portion of OAS payments (OAS Recovery Tax).
To Delay or Not to Delay?
You may elect to delay your OAS to get more money each month, but almost nobody does (less than 3% of people). Even if you do wait, the benefit isn't as dramatic as CPP. OAS increases by 0.6% for each month you delay past age 65, up to a maximum of 36% if you wait until age 70.
How Our Team at Weatherill Wealth Can Help…
We create a detailed financial plan, using the various CPP numbers to provide you with more data to make your decision on taking CPP or delaying it to receive more:
- We check for red flags first - Ensuring you have adequate resources, a good understanding, and a solid financial plan to help you make decisions on your CPP.
- We evaluate the role of you registered investment accounts - Your RRSP, RRIF, LIRA, & TFSA are important investment accounts with great tax benefits. We want to make sure you use them to your advantage.
- We plan the timing - We provide custom tailored guidance on the optimal time to begin receiving your CPP.
- We minimize taxes - Our goal is for you to keep your hard-earned money, in your pocket by minimizing the taxes paid by you… and your estate.
In Conclusion…
Retirement planning isn't a one-size-fits-all solution. When you qualify for CPP and OAS, how much you've earned over your lifetime, and how you manage your savings, matter. We are here to help analyze all components of your financial future to ensure you make the best decision for you and your family.
-Brad Weatherill