Paul Chapman
Senior Portfolio Manager & Wealth Advisor
October 29, 2026
“Epistemia: a structural condition where the smooth, fluent language of artificial intelligence tricks people into feeling they know something without doing the hard work of checking the facts.” – Computer Scientist Walter Quattrociocchi coined the term recently
Note that the contents of this memo are all my thoughts, and not the views of RBC Dominion Securities. As well, no part of this content was AI-assisted or created.
YOU CAN LISTEN TO THE ABBREIVATED PODCAST VERSION OF THIS NOTE HERE
Friends & Partners,
Like a consummate Canadian, I’m going to open by apologizing – as we need to beat this dead horse topic that is AI. We’ve all been suffering from some AI fatigue I’m sure. But we need to address it here simply because it has become such a driving force, not only in stock and bond markets, but in the economy. If it’s a bubble, it’s an everywhere bubble. Where it goes, so will much else, for better or worse.
There continues to be stress across the AI landscape. The pace of capital spending, and the borrowing to pay for it, was never going to be sustainable. Investors have worried that AI companies are spending too much on data centers. These companies' once-ample free cash flows have turned negative, forcing them to borrow significantly. Concerns have mounted that they are driving up financing costs and won't generate sufficient returns to justify their huge investments. And now, another concern for the market is if enough capital even exists to finance everyone's ambitious AI spending plans?
That reality is beginning to get priced more appropriately, which is a healthy development. A market that separates winners from losers based on realistic earnings and return on investment is far healthier long term than one that rewards every AI headline equally. So, we market-driven tightening access to capital is healthy for the AI boom, resulting in more efficient capital allocation and reducing over-investment risks.
Let’s put it this way – many won’t be aware that there is a “stealth/rolling correction” underway in the stock market. Indexes sit near their highs, but 85% of S&P 500 Index names are more than 10% off their highs, and 60% are more than 20% off their highs. But since the large tech/AI companies dominate the market, it’s difficult to see that is occurring.
Most folks are aware of the bubble in chips, memory, optics, storage and LLM providers. Now it has spread to lift shares in many industrials involved in building or power to the traditionally boring utilities. Mining gets a lift since the data center buildout needs critical minerals and copper. And from a geographic perspective, pick an equity market and there is often a good amount of AI exposure. This isn’t just stocks, same goes for credit markets (bonds).
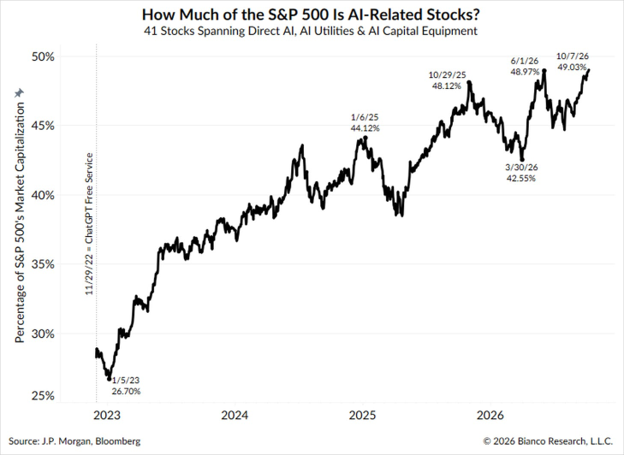
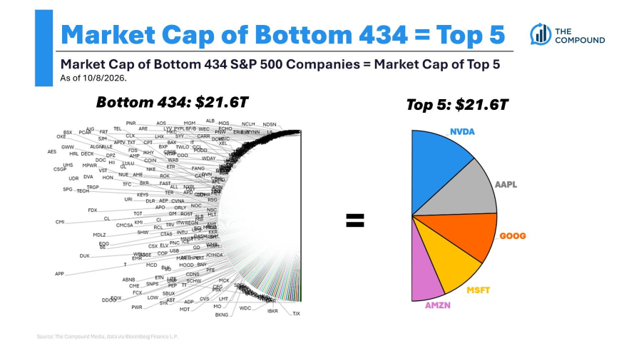
AI makes up over half of the US stock market and influences even more than that. If you thought a passive index fund is well diversified, think again:
The AI buildout is bigger than any of the world’s infrastructure spends – ever. Measuring the spend vs the size of the economy, the only past infrastructure spend that comes close was the railway expansion back in the late 1800s. The kicker is that every one of these episodes was a bubble, where investment returns burst part way through the actual buildout. The railway bubble lasted 20 years and railway investors enjoyed strong returns in the 1870s and very poor results in the 1880s even as the infrastructure spend and buildout persisted. The internet was similar, 2000 to 2003 was abysmal for stocks but cable continued to be laid. So, I suppose you want to leave the party before turning into a pumpkin… Or position the portfolio accordingly since timing that stuff is impossible.
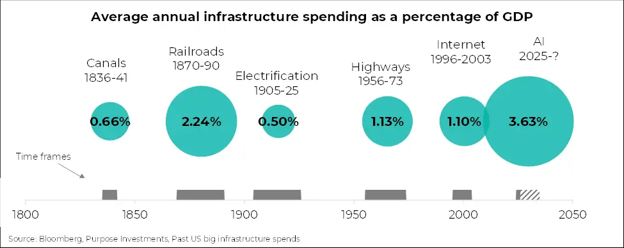
Certainly, there are reasons to be concerned - analogies arise comparing it to the bubble of the early 2000’s tech episode, as well as the credit excesses of the Great Financial Crisis in 2008.
Bond markets are usually seen as the ‘smarter money’ market and are doing a good job of reigning in the bad actors in that ecosystem, I could argue. We’ve seen the cost of borrowing shoot up for the more speculative and challenged businesses in that sector, and this can help deflate the bubble rather than burst it.
Markets have gotten somewhat ‘healthier’ as valuations come back a bit, and earnings keep on rocking across the board. Even outside the US, the All-Country World ex US MSCI's forward earnings are up 41% year over year, while forward revenues are up 11.0%. The global economy is doing well.
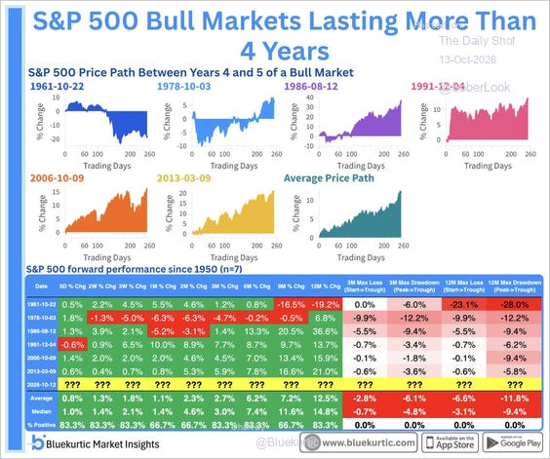
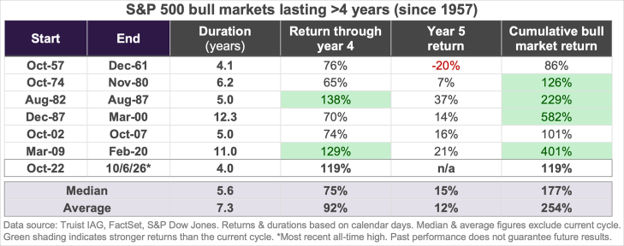
And just because markets have run for a while doesn’t mean it will end soon – there’s a famous saying in finance that markets don’t die of old age. Of the six previous bull markets that lasted at least four years, five gained further ground in their fifth year, with an average fifth-year return of 12%.
US midterms are around the corner, and many expect lots of noise around them. We will see. Here's something worth knowing on that front: since 1950, the S&P 500 has averaged a 15.4% gain in the 12 months following midterm elections, finishing higher in all 19 completed periods.
Yields continue to remain high, which is more of a ‘return to normal’ in my view as I wrote in last month’s Partner Memo. I’m non-consensus when I note that I think the narrative will likely flip in 2027 – we may see a reversal in yields sooner than later, driven by a paring back of hawkish Fed expectations. This year’s bond selloff reflects a dramatic repricing from 3 expected rate cuts by the end of 2027 at the outset of the Iran war to roughly 3 additional hikes today. This shift is likely excessive as inflation and labor market data surprises have rolled over.
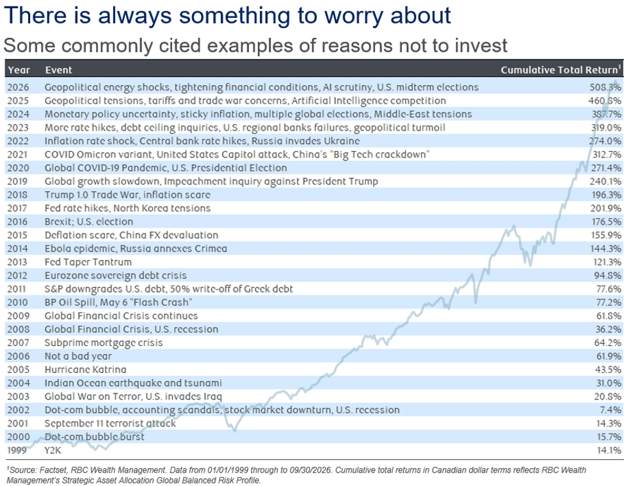
So, history alone doesn't tell us where the opportunities are today. Remember, discipline and a thoughtful portfolio construct pay off. We are all in it now and we believe the key to navigating will be to monitor its path, be aware of your exposures, be opportunistic and be prudent by ensuring your portfolio has adequate diversification offsets. The wall of worry may be in a bit of a different location than it was in past episodes…
Other Interesting Things To Highlight
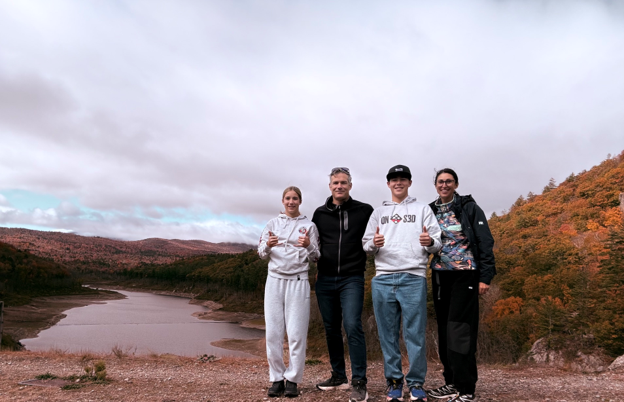
I hope everyone had a wonderful thanksgiving – we visited our son who is attending high school in Vermont where the colours are about as stunning as they can get.
I was excited to be the presenting sponsor for the Georgian Triangle Humane Society’s marquis annual event last month, where they hosted an incredible performance by the Great Canadian Dueling Pianos. A great event for a great cause, where we raised $32,000 that evening.
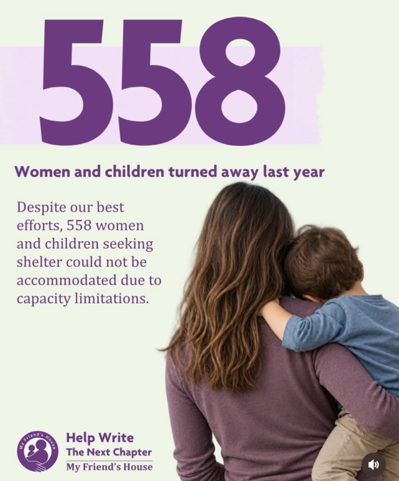
I was proud to also support My Friend’s House HeART of Red: Live Painting Experience event at Osler Ski Club in October as the title sponsor. They need our support to expand to be able to help more women and children:
In November, I am hosting a very small event on ‘tax aware’ strategies – this will be for selected partners and accountants and tax advisors. There are strategies and structures out there that many accountants may not even be aware of, and we’re going to dig into those over a dinner event at a nice restaurant in Toronto.
We will also be hosting our 4th family office event in November, which will bring together many of the top family offices in Canada. These are very limited events for selected family offices and partners, and we have some large institutions joining us to discuss different approaches to Alpha in managing capital.
I Always Add All Of The Negative Points to Ruin Your Day
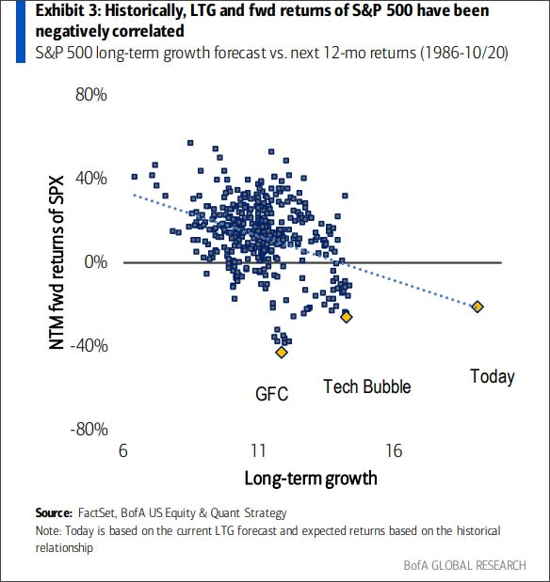
I wrote about this last month and will continue to – given where assets are valued currently, don’t expect similar returns in traditional stock markets like you’ve experienced in the past. Value will be added in the portfolio construct and finding opportunities with the right strategies and managers. This chart doesn’t portend great stock returns from here:
So, you’d better be diversified outside of the traditional ‘stuff’, because traditional allocations ain’t working:
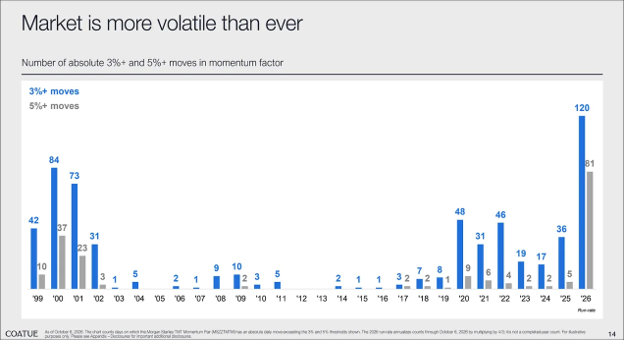
As I have written about and continue to remain the case, the market is more volatile than ever:
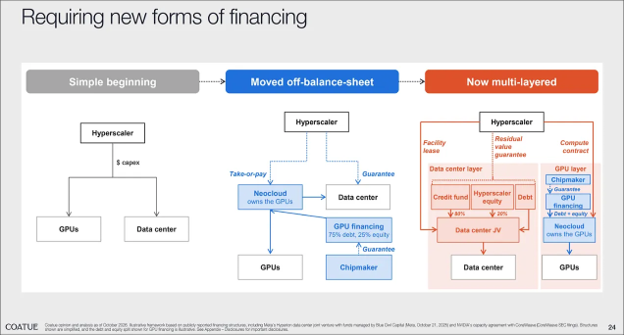
Complexity is not usually a good thing, and Wall Street has lots of precedent where it goes sideways… Maybe this time it’s different?
Let’s see how the data center buildout continues then…
There Are Always A Number Of Positives To Consider
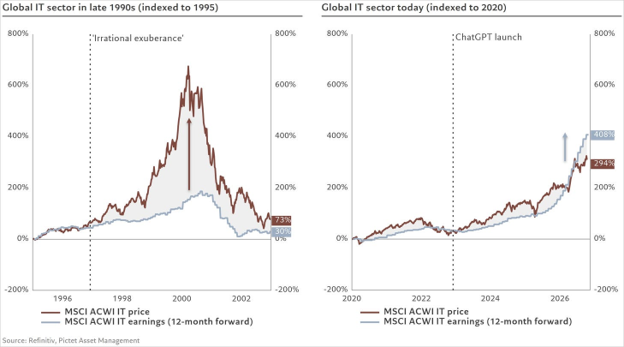
Unlike the dot-com bubble, when global technology stocks surged far ahead of earnings, the current rally has been supported by stronger earnings growth, which is VERY different setup.
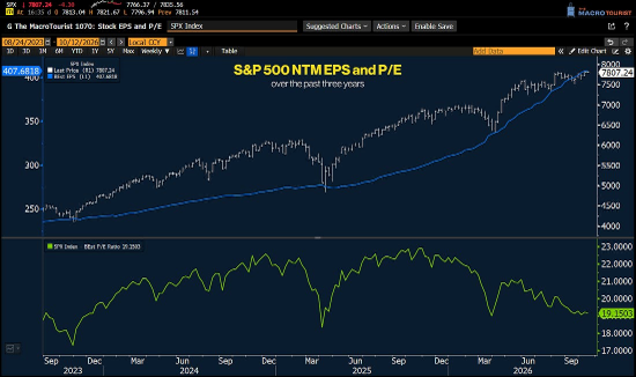
And it’s tough to argue that markets are way overpriced here, we are back to 19x next-twelve-months P/E. That’s high, but far from nosebleed.
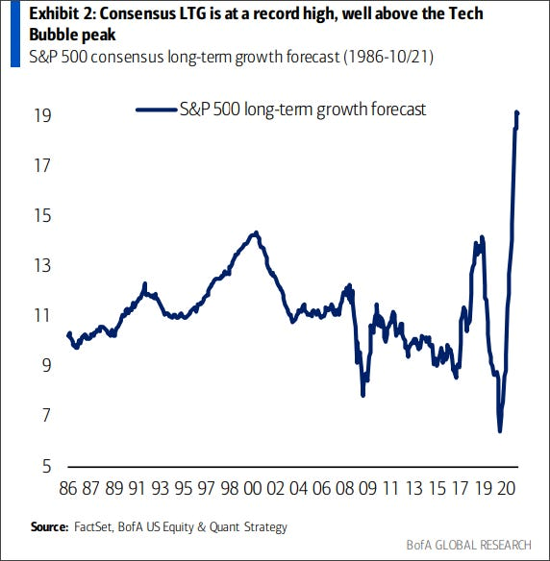
This can be construed as positive or negative… BofA: Consensus Long-term growth forecast is at all-time record highs.
Since 1974, every S&P 500 bull market that reached its fourth anniversary has gone on to complete a fifth year, with the four most recent cases delivering double-digit gains without a correction exceeding 10%.