Shawn Mottahedeh
CFA, Lead Strategist & Associate Portfolio Manager
September 17, 2026
- The AI-driven bull market remains in its early innings, though elevated rates, debt, and geopolitics pose important risks.
- The rise in US rates is on our radar. But we see a reasonable chance they are near a short-term peak after the Fed’s recent actions.
- Canada’s position is improving as a resource powerhouse for the AI and reindustrialization boom; recent policy shifts are encouraging.
AI Growth vs. Macro Risks
The current bull market has been powered by artificial intelligence and its cascading effects across industries. Despite ongoing talk of an investment bubble, many of the indicators we observe point to this still being the early phase of development. Oversupply or demand shortfalls remain years away. As a result, we expect a multi-year economic growth story as AI’s productivity gains and capital spending ripple through the broader economy.
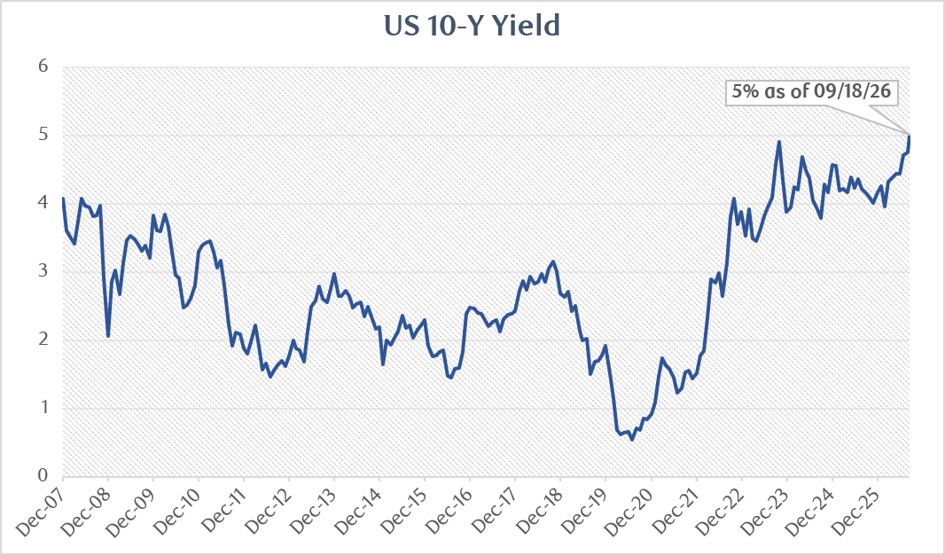
The principal risk that could interrupt this trajectory is the macro backdrop, specifically the interplay of debt, inflation, geopolitics, and interest rates. The chart below shows US 10-Y yields, which is a widely followed proxy for the US bond market. A sustained move above 5% in this indicator, especially given how low rates have been in recent years, could cause market fears to spike. As you can see in the chart, we are testing those levels now, with yields among the highest in decades.
The drivers of the rise matter and are often lost amid short-term volatility. If rates are rising for good reasons, there is less cause for worry. For example, rates can climb because growth expectations are improving, which we believe is part of the story today. They can also rise because debt supply is growing. This is currently the case as hyperscalers are racing to fund AI infrastructure, which we believe is the right thing to do when the prospects for growth are so favorable.
But rates can also rise for bad reasons, namely inflation expectations and/or a concern about Federal Reserve independence. The latter have dominated public attention and, in our view, are overstated. Current inflation looks more like a temporary byproduct of the Iran conflict and its effect on oil prices. We expect this to ease once that episode concludes.
Incidentally, there is a reasonable chance rates are approaching a short-term peak. The Fed has demonstrated sufficient independence from political pressure and has remained hawkish enough to leave room for positive surprises if incoming inflation data soften. Consequently, we have extended duration in the bond portfolio to lock in these higher yields while they remain available. At the same time, we respect the residual macro risks and have positioned other holdings – particularly in materials and energy – to benefit should inflation concerns persist and yields continue to rise.
Canada’s Improving Global Position
The last point relates well to our changing views on Canada. Long-time readers know we have been cautious on our home country for years as it has lagged in global competitiveness and its housing bubble was correcting. Those prospects are shifting. Canada has always been resource-rich. Its issue has been leveraging this privilege. As Jon Gray of Blackstone put it, “Canada is a sleeping giant, economically.” This is a particularly favorable position to be in as the world needs our resources to support the AI investment boom and the reindustrialization underway in developed economies.
It looks like the current government is committed to taking advantage of this moment. This week’s Canada Investment Summit underscored the change. Hosted by Prime Minister Mark Carney in partnership with major Canadian pension funds, the gathering produced nearly $500 billion in new investment commitments spanning energy, critical minerals, infrastructure, AI data centers, and related projects. This is all in the context of several major policy and tax shifts that aim to make Canada a better place to invest.
Whether in Canada or not, savvy investors need to maintain adequate exposure to the basic inputs required for the next phase of global growth, including oil, copper, and critical minerals. Domestic access to these resources is a structural advantage we intend to use. Clients should therefore expect their allocation to Canada in general, and to these sectors in particular, to increase in the months ahead.
A Final Note Re: Sentiment and Sticking to Your Plan
Last week, the AAII investor survey showed that investors are among the most pessimistic they have been in years (see chart below).
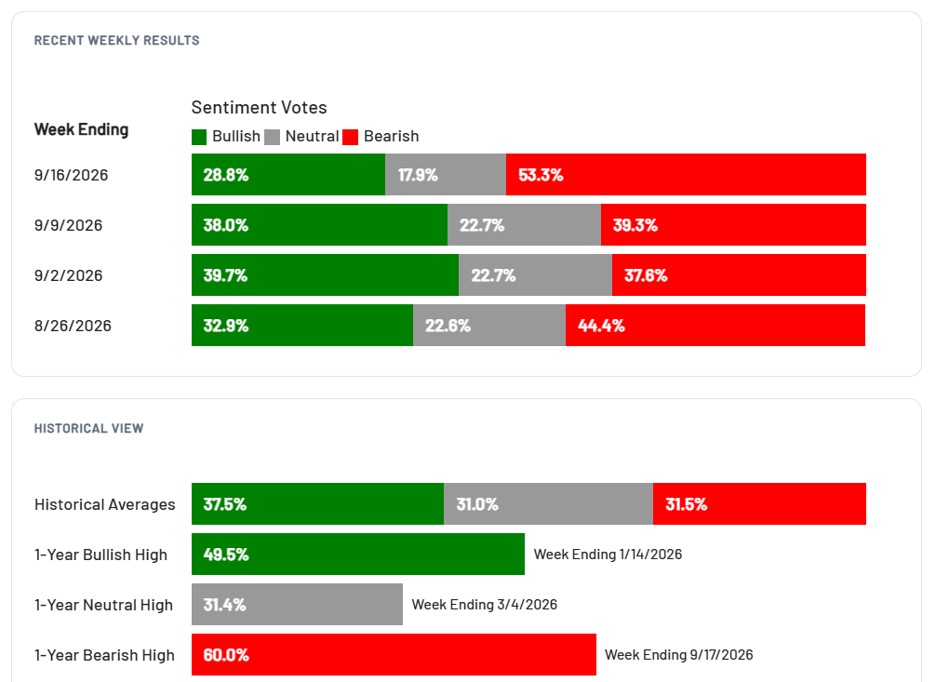
This jives with the conversations we have been having with investors; many people are worried about market momentum fading and have become increasingly sensitive to every market downturn. Our word of caution here: nobody knows what the market is going to do in the weeks and months ahead. That said, a correction of 5, 10 or even 15 per cent is entirely possible. Not because of the specific market we’re in today. But because events like these can happen effectively any time. What’s crucial is that you develop a plan and stick to it. This will ensure you are in the right emotional mindset to continue to compound returns in the years to come. We can help you with this, so please reach out if you haven’t spoken with us about this already or could use a little refresh on our strategy. In the meantime, you can expect us to stay vigilant on your behalf.
RBC Dominion Securities Inc.* and Royal Bank of Canada are separate corporate entities which are affiliated. *Member-Canadian Investor Protection Fund. RBC Dominion Securities Inc. is a member company of RBC Wealth Management, a business segment of Royal Bank of Canada. ® / ™ Trademark(s) of Royal Bank of Canada. Used under licence. © 2026 RBC Dominion Securities Inc. All rights reserved. This information is not intended as nor does it constitute tax or legal advice. Readers should consult their own lawyer, accountant or other professional advisor when planning to implement a strategy.